
How much is enough to contribute to retirement?
Written by Kyle Jeacocks, specialist in the Group Savings and Investments team at Allan Gray
Starting early, investing appropriately and remaining invested are key to achieving a comfortable retirement. But contribution levels are also critical. Kyle Jeacocks explores how different contribution strategies can shape retirement outcomes over a 40-year career, and what employers and employee benefit consultants can do to help members improve their retirement readiness.
Time in the market and investment growth do most of the heavy lifting required to secure a comfortable retirement. However, the level of contributions made throughout a member’s working life is equally important for achieving the desired retirement outcomes.
While contributions reduce the budget available for day-to-day spending, they benefit from compound growth and can accumulate into a reliable source of financial security for members. Conversely, under-prioritising them can create a significant gap between expected and achievable retirement outcomes, leading to budget constraints when members begin to draw an income.
Employers and employee benefits consultants often use the concept of a replacement ratio to assess retirement readiness. This measures the proportion of a member’s final salary that can be sustained in retirement. A commonly referenced target is approximately 75%, yet relatively few South Africans achieve this level, highlighting the importance of considering contributions relative to the retirement income they are expected to generate.
Long-term investing requires discipline. While there is no one-size-fits-all approach to retirement investing, it is imperative to have a structured plan. Members need to have a clear budget and live within their means, as this makes it easier to identify how much income needs to be replaced when working is no longer an option.
Life has a way of pulling individuals in a variety of unique directions, so while some members prioritise flexibility early in their careers, contributing relatively less initially (and then increasing their contributions later), others contribute more aggressively from the outset and manage their budget around this decision. While these decisions are often out of a member’s hands as life’s responsibilities and unexpected events take hold, it is important to understand how they can influence retirement outcomes.
Graph 1 compares four contribution journeys for Individual X, and their respective replacement ratios achieved over time. Individual X starts their career at age 25, earns a gross monthly salary of R30 000 – adjusted for 5% inflation annually over a 40-year investment horizon – and has no accumulated retirement investments. The projected outcomes – i.e. the replacement ratio achieved as shown in the brackets on the graph – are based on an assumed nominal growth rate of 11% (inflation plus a real return of 6%), with no previous withdrawals, no additional contributions and a 4% drawdown rate in retirement, with the goal of achieving a 75% replacement ratio.
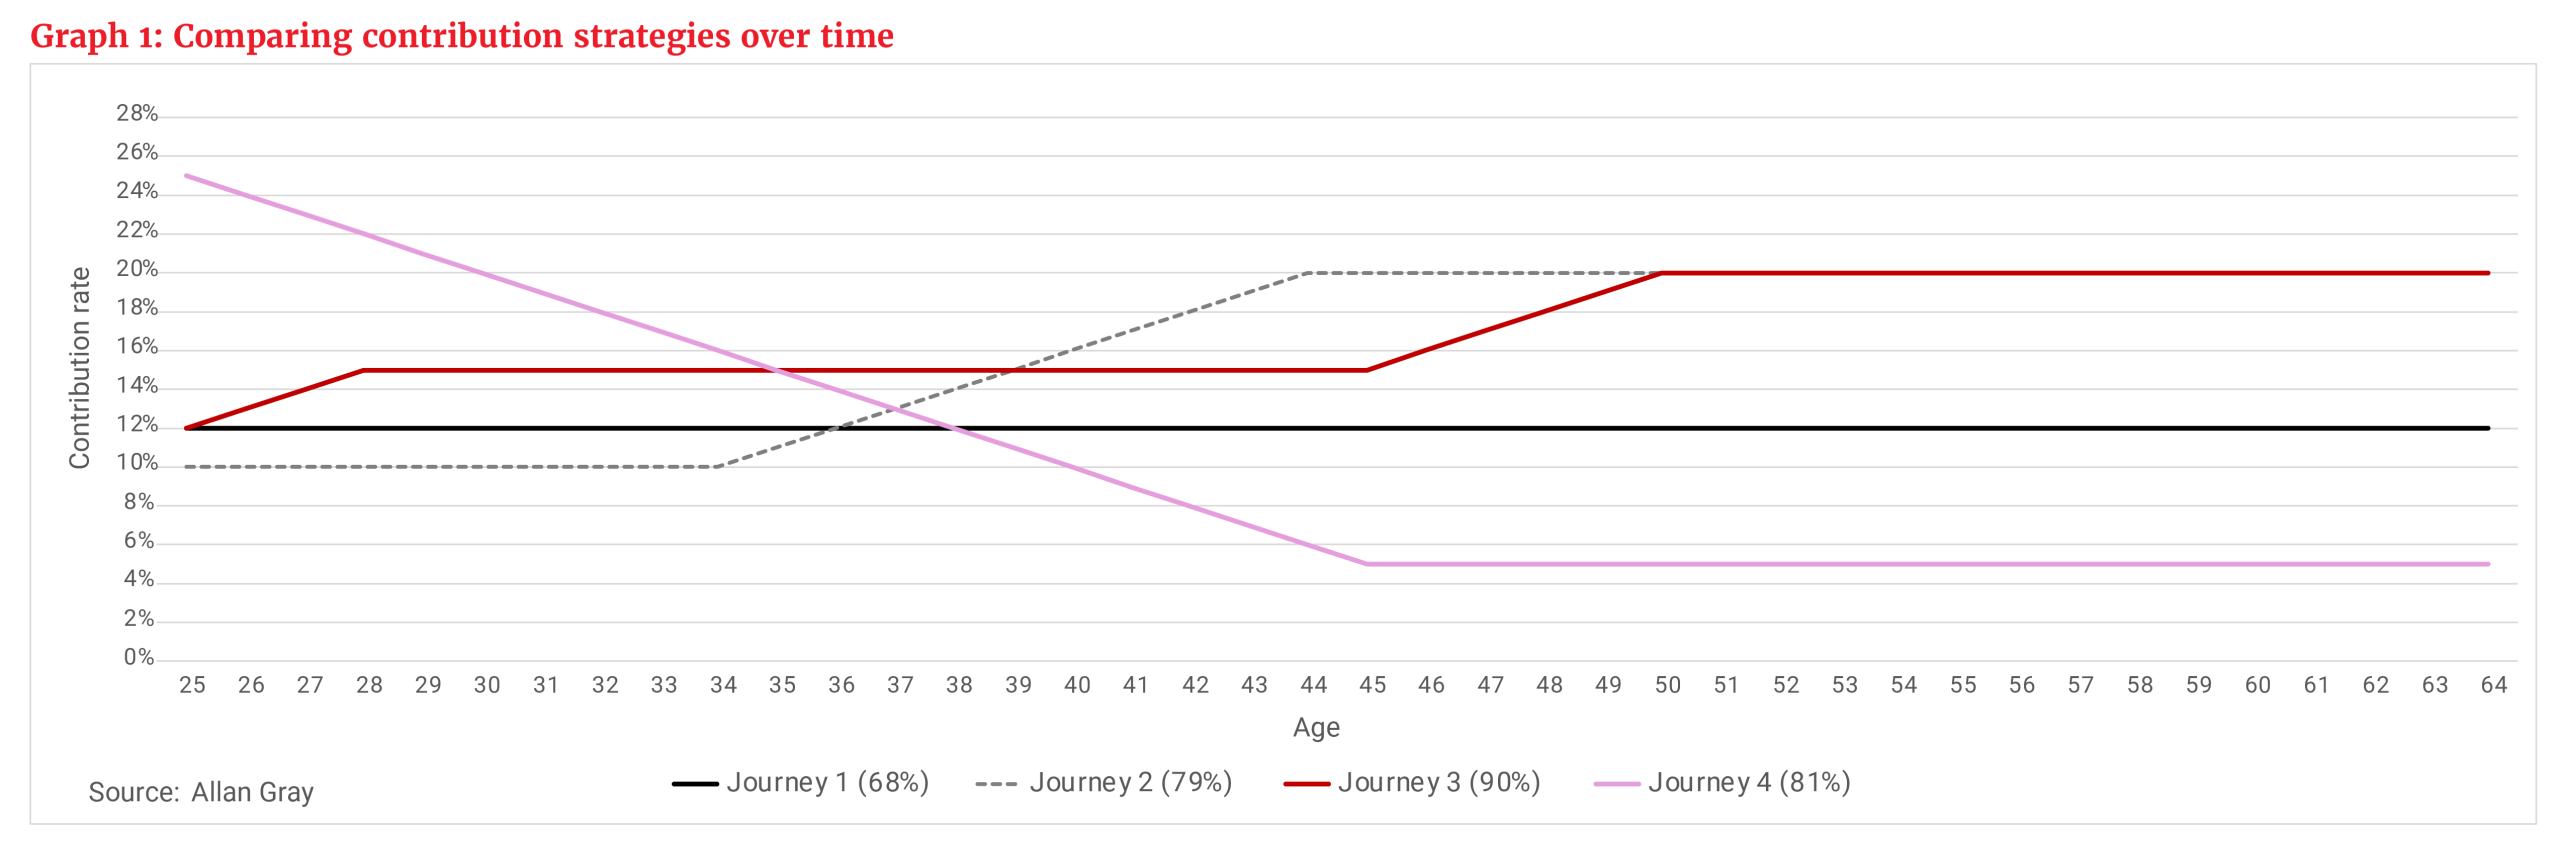
- Journey one (black): The steady contributor
This illustrates the projected replacement ratio achieved if Individual X contributes a flat 12% of their inflation-adjusted salary throughout their career. - Journey two (grey): Starting small and increasing as the years pass
This illustrates the potential replacement ratio achieved if Individual X contributes 10% of their inflation-adjusted salary for the first 10 years of their career, then scales up the contribution amount to 20% in increments of 1% per year. - Journey three (red): A phased approach to investing more
This illustrates the replacement ratio that could be achieved if Individual X initially contributes 12% of their inflation-adjusted salary, before increasing contributions by 1% per year until reaching 15%. This rate is maintained until age 45, after which contributions increase by a further 1% per year until reaching 20%, which is then maintained until retirement. - Journey four (lilac): Front-loading retirement investing
This illustrates the projected replacement ratio that could be achieved if Individual X contributes 25% of their inflation-adjusted salary, before scaling contributions down by 1% per year until reaching 5%, then maintaining the 5% contribution rate until retirement.
Rather than assuming that a specific rand amount saved each month will suffice, employers and consultants should encourage members to think about what percentage of their salaries they should be investing now to fund their later years. While this may seem complicated in isolation, there are tools that exist for this exercise. These tools aim to give members a clear picture of what they will need to do to improve their outcomes – which could include delaying retirement where possible. Many umbrella fund providers, including Allan Gray, make them available on request for active schemes.
Ultimately, sufficient contributions started early enough and made consistently, combined with prudent manager selection and appropriate asset allocation, should lead to positive outcomes.
Making time count
A 40-year career provides a meaningful opportunity to build retirement investments. Top-quartile investment managers, such as those monitored by respected manager watch surveys, have achieved real annual returns above inflation of 7% over multi-decade periods, highlighting that manager selection is crucial to achieving retirement success.
However, retirement outcomes are shaped by more than simply time and investment returns. Contribution decisions and the preservation of investments play an important role in determining retirement readiness. The challenge is making time work as effectively as possible.